VAT on Digital Services: The Threshold That Catches Small Sellers First
Digital services sold across borders are taxed where the customer belongs, not where the business is based. Since 1 January 2015, telecommunications, broadcasting and electronically supplied services within the EU have followed this destination principle, leaving small sellers to navigate a patchwork of thresholds, platform rules and evidence requirements that determine when they must charge foreign VAT and which simplified scheme can spare them from registering in multiple countries.
Customer location governs B2C, fixed establishment governs B2B
The EU and UK rules split the world into two customer types. For business customers, the place of taxation is the country where the business is registered or where it has fixed premises receiving the service. For consumers, it is where they are registered, have their permanent address, or usually live. This distinction matters because it determines which VAT rate applies and, in some cases, whether VAT applies at all. A UK-based developer selling software to a German company faces different rules than one selling the same subscription to a German individual. The shift from origin-based to destination-based taxation was designed to stop large suppliers from clustering in low-VAT jurisdictions, but it dumped the compliance burden on small sellers who now must identify customer location for every transaction.
The €10,000 threshold that keeps small sellers domestic
The EU introduced a yearly threshold for cross-border online sales to other member states. Below this figure, sales are treated as domestic supplies taxed at the seller's home rate rather than the customer's. The European Commission explicitly designed this to support start-ups and micro-businesses, allowing them to apply the origin principle while their cross-border volume remains modest. Some member states may exempt established small businesses from VAT entirely if annual turnover stays below a set threshold, though these exemptions do not remove the obligation to track cross-border sales. The threshold is calculated across all EU member states combined, meaning a seller with significant sales in multiple countries may need to switch to destination-based taxation.
When platforms become the taxable supplier
Selling through a marketplace can remove the VAT obligation from the seller entirely. Under EU rules, when services are provided through an electronic interface, the underlying provider is treated as supplying the service to the platform operator, who then supplies it onward to the final customer. UK guidance puts this more directly: if digital services reach consumers through a third-party platform or marketplace, the platform is responsible for accounting for VAT instead of the seller. This deemed-supplier treatment applies unless the actual provider is explicitly indicated as the supplier at the point of sale. For small sellers, this creates a critical distinction between direct sales, where they must handle location evidence and VAT registration themselves, and platform-mediated sales, where the compliance burden shifts to the marketplace operator. Electronic interfaces can be presumed to act in their own name for supplies made through their networks unless stated otherwise.
The two-item evidence rule that trips up solo operators
Identifying customer location requires more than asking for a country. EU guidance lists multiple evidence types: billing address, IP address or geolocation, bank details, and the SIM-card Mobile Country Code. The critical detail is that two non-contradictory pieces of evidence are required to establish where the customer belongs. UK guidance expands the acceptable list to include fixed landline location and other commercially relevant information, and specifies practical collection methods: sellers should obtain either the consumer's billing address with country or telephone number with country dialling code at point of sale, and may rely on payment-service-provider notification advice carrying a two-digit country code. Relying on a single signal—a customer-selected dropdown menu, for instance—does not meet the standard. The evidence must be gathered at or before the transaction and retained in forms that tax authorities can examine.
Ten years of record-keeping for platform operators
Retention rules vary by role. Electronic interfaces must keep records on the supplies they facilitate for ten years from the end of the year in which the supply was carried out, according to 2020 EU explanatory notes on VAT e-commerce. This explicit decade-long requirement applies to marketplace operators, not necessarily to individual sellers using those platforms. For sellers operating outside platform structures, the brief does not contain verified retention periods for invoices and VAT records in individual jurisdictions, leaving a gap that sellers must fill with local advice. The ten-year rule for platforms reflects the complexity of tracing multi-party transactions where the interface sits between provider and customer, and the extended period accounts for the delayed discovery risks inherent in cross-border audit cooperation.
The three ways small sellers fail
The rules contain specific traps. Some sellers continue treating all digital sales as domestic, missing that the 2015 shift moved telecommunications, broadcasting and electronically supplied services to destination-based taxation regardless of seller size. Others rely on single-source location evidence, unaware that EU guidance mandates two non-contradictory items and that tax authorities can reject VAT returns that fail this test. The third failure point is threshold timing: the €10,000 limit is assessed yearly, and crossing it mid-year triggers obligations for the period from that point forward, though the brief does not contain verified rules on the exact date from which VAT becomes due after threshold breach. Sellers who discover their crossing only at year-end may face uncollected VAT, penalties, and the impossibility of retroactively charging customers. The compliance burden is front-loaded: evidence systems must be in place before the first foreign sale, not after volume justifies the investment.
A seller remains compliant only when customer location is documented to the two-item standard, platform status is identified for each sales channel, and the applicable threshold or simplified scheme is tracked against accumulated cross-border revenue before the first euro leaves domestic territory.
Sources
- European Commission, “The basic EU VAT rules for electronically supplied services” — taxation-customs.ec.europa.eu, 2015
- European Commission press corner memo 16/3746, “Modernising VAT for e-commerce: Question and Answer” — ec.europa.eu, 2016
- European Commission — vat-one-stop-shop.ec.europa.eu, 2015
- European Commission, “Explanatory Notes on VAT e-Commerce” — vat-one-stop-shop.ec.europa.eu, 2020
- European Commission, “VAT for businesses” — taxation-customs.ec.europa.eu, 2024-05-22
- GOV.UK, “Defining digital services” — gov.uk, 2014-12-19
More from Markets & Regions
Section index
Casino en ligne sans licence ARJEL
Dans le domaine des jeux d'argent sur Internet , de nombreux opérateurs ne sont pas placés sous le contrôle de l'ARJEL (devenue aujourd'hui ANJ - Autorité…
Casino Royal Vegas en ligne
Parlons d’abord des bonus. Chaque joueur qui rejoint la plateforme bénéficie d’un package de bienvenue exclusif. En plus du bonus d’inscription, Royal Vegas…
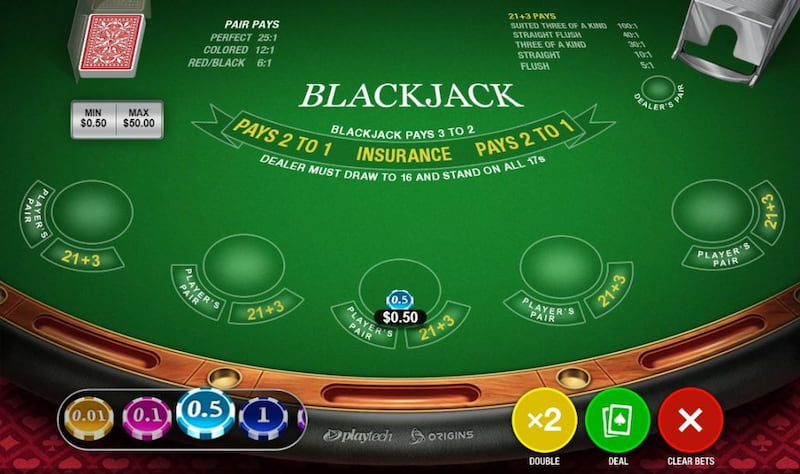

Cómo jugar al blackjack: reglas y consejos
El blackjack es probablemente el juego de cartas que más se juega en los casinos de todo el mundo y Perú no es una excepción. Es un juego muy atractivo para aquellos…